Overview & RoleVisão geral e papel
OverviewVisão geral
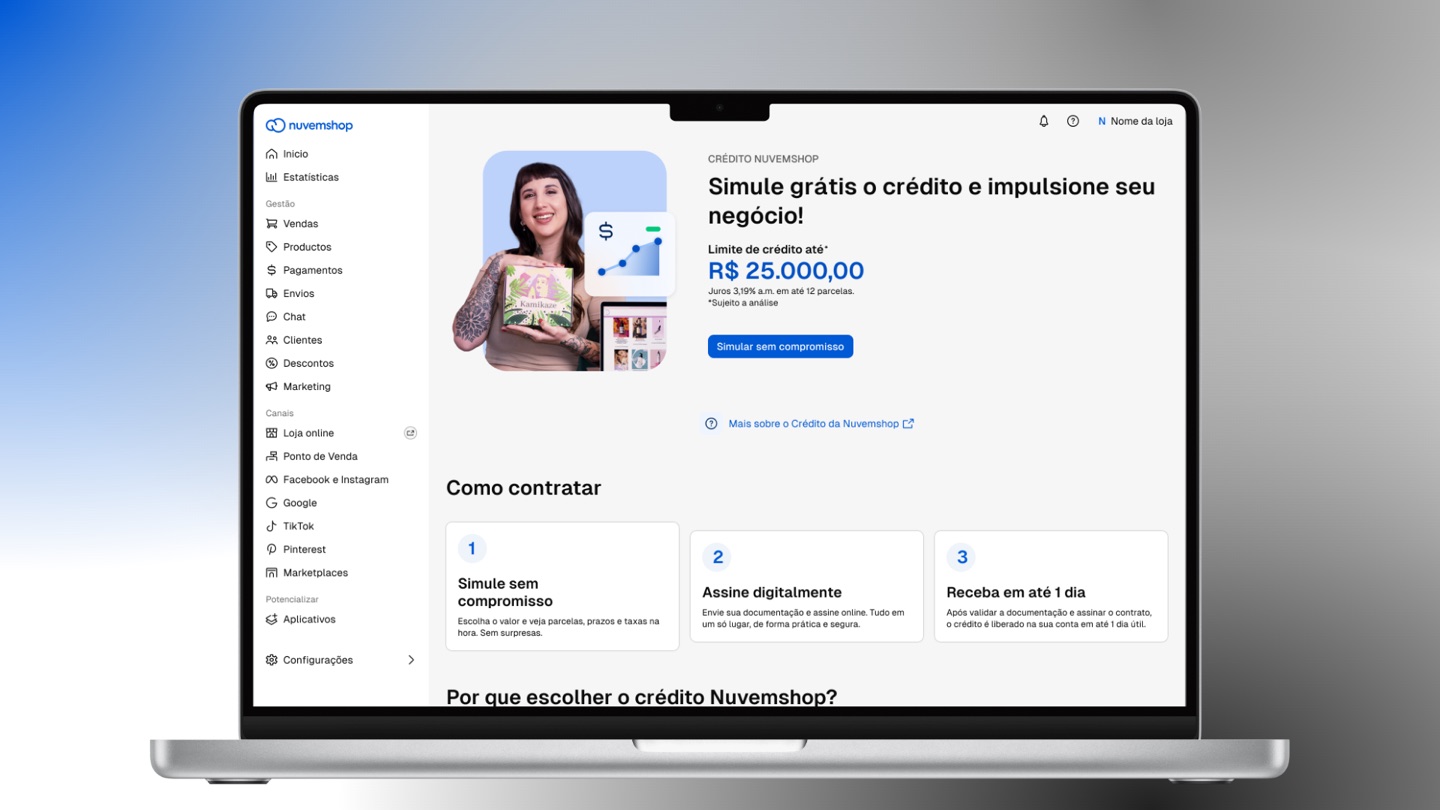
Lending is Nuvemshop's credit product. The merchant requests the loan, follows the contract and renews it without leaving the store dashboard. Mova, our partner, is the lender behind it.O Lending é o produto de crédito da Nuvemshop. O lojista pede o empréstimo, acompanha o contrato e renova sem sair do painel da loja. Quem empresta é a Mova, nossa parceira.
RolePapel
I owned the design of the journey, from research to delivery. I ran the interviews, drew the flows and took the design decisions to Mova. Product, engineering and CX built it with me.Fui o designer responsável pela jornada, da pesquisa à entrega. Conduzi as entrevistas, desenhei os fluxos e negociei as decisões de design com a Mova. Produto, engenharia e CX construíram comigo.
BackgroundContexto
Small and mid-sized merchants on Nuvemshop are almost always short of cash. The squeeze shows up when it is time to restock, or when an ad campaign finally starts working and there is no money to scale it. Getting a loan elsewhere means leaving the platform, gathering paperwork and waiting weeks. Nuvemshop already had the sales history to skip most of that.Lojista pequeno e médio na Nuvemshop está quase sempre apertado de caixa. O aperto aparece na hora de repor estoque, ou quando o anúncio finalmente engata e falta dinheiro para escalar. Pegar empréstimo fora significa sair da plataforma, juntar papelada e esperar semanas. A Nuvemshop já tinha o histórico de vendas para encurtar quase tudo isso.
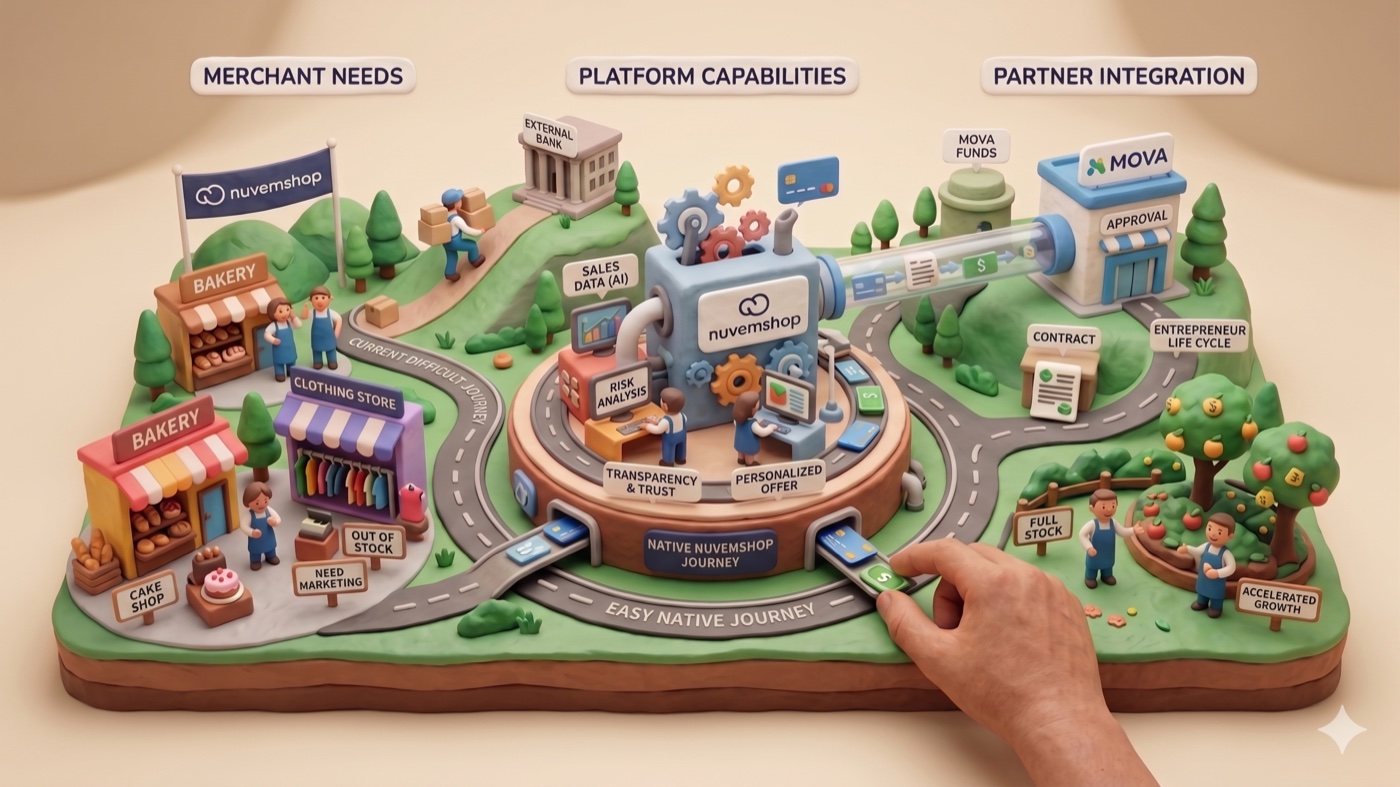
The hard part was doing it without the result looking like a third-party product bolted onto the dashboard. Mova runs the credit engine, but the merchant should only have to trust one brand. The journey also had to be straight about cost and term, and keep working through the months of repayment — which is when most of the questions come up.A parte difícil era fazer isso sem parecer produto de terceiro colado no painel. A Mova roda o motor de crédito, mas o lojista só deveria precisar confiar em uma marca. A jornada também precisava ser direta sobre custo e prazo e continuar funcionando ao longo dos meses de pagamento — que é quando aparece a maior parte das dúvidas.
The ProcessO processo
Research came first, design after. Every stage went through Mova and engineering before it became a screen.A pesquisa veio primeiro, o desenho depois. Cada etapa passou pela Mova e pela engenharia antes de virar tela.
We sat with the Mova team in every phase. That is why the seam between the Nuvemshop screen and the credit engine never shows.Sentamos com o time da Mova em todas as fases. É por isso que a emenda entre a tela da Nuvemshop e o motor de crédito não aparece.
Understanding the ProblemEntendendo o problema
Three things were stopping merchants. Trust: the terms were vague, and Mova's brand meant nothing to them. The contract: dense legal language that never said plainly what would be charged, or when. Renewal: a merchant with an active contract had no way to follow it, or to ask for more credit without calling support.Três coisas travavam o lojista. Confiança: os termos eram vagos e a marca da Mova não dizia nada a ele. Contrato: linguagem jurídica densa, que nunca dizia com clareza o que seria cobrado, nem quando. Renovação: quem tinha contrato ativo não conseguia acompanhar nada nem pedir mais crédito sem ligar para o suporte.
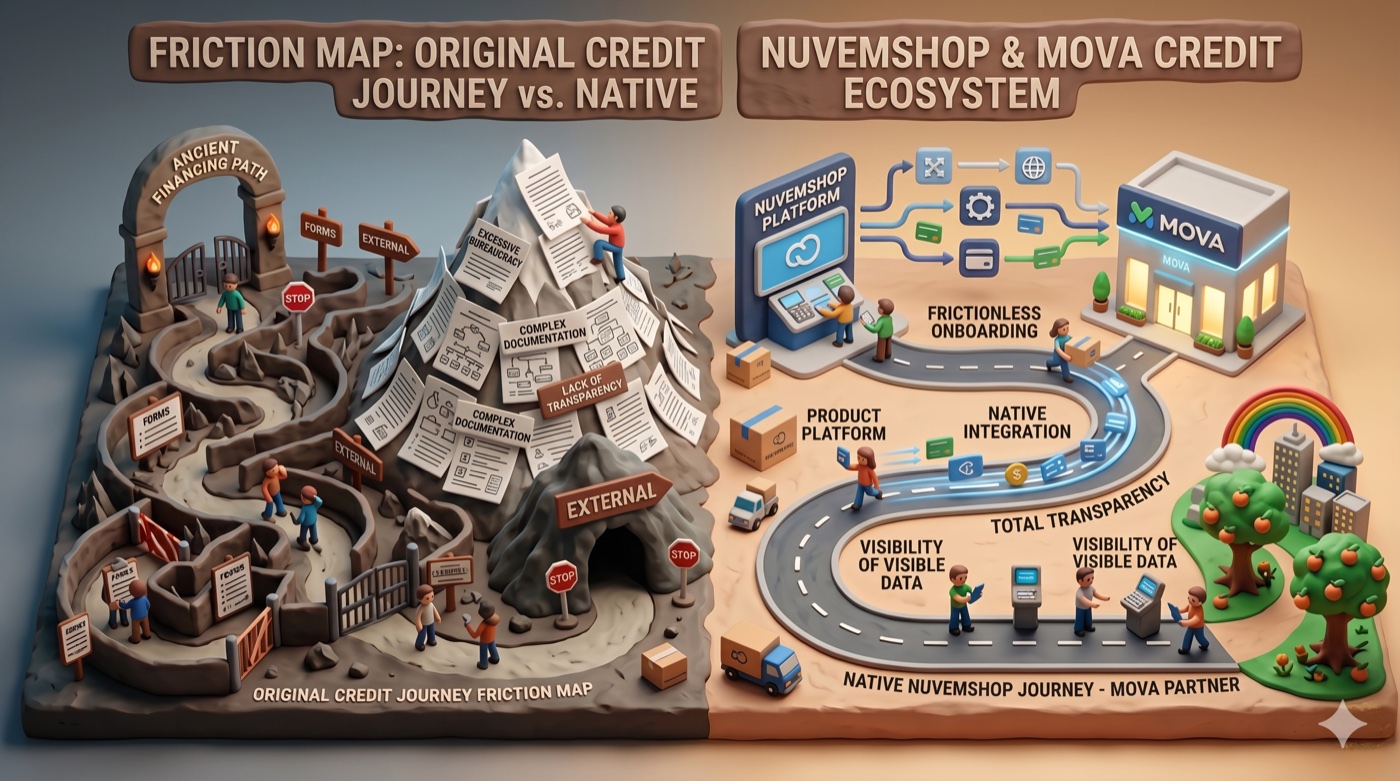
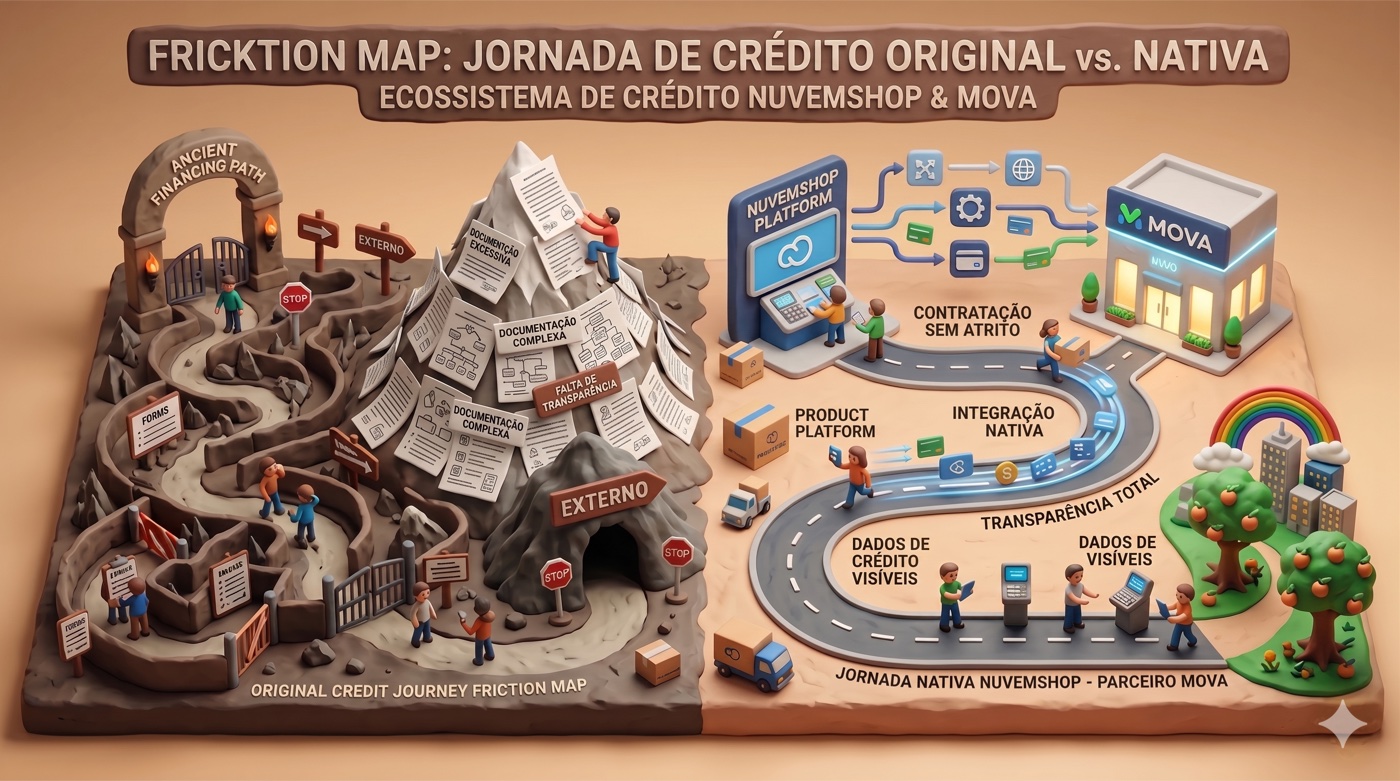
None of the three is an integration problem. All three come down to whether a merchant believes a loan that shows up inside their own dashboard. That trust is what the design had to earn.Nenhuma das três é problema de integração. As três são sobre o lojista acreditar num empréstimo que aparece dentro do painel dele. Era essa confiança que o design tinha que conquistar.
What research showedO que a pesquisa mostrou
The evidence came from three places: 15+ merchant interviews, with people who had taken credit and people who had not; twelve months of funnel data, showing where merchants dropped off; and workshops with Mova, to agree on shared principles. Four studies came out of it.A evidência veio de três lugares: mais de 15 entrevistas com lojistas, gente que já tinha pegado crédito e gente que não; doze meses de dados de funil, mostrando onde o lojista desistia; e workshops com a Mova, para acertar princípios comuns. Saíram daí quatro estudos.
Base potential analysisAnálise de potencial da base
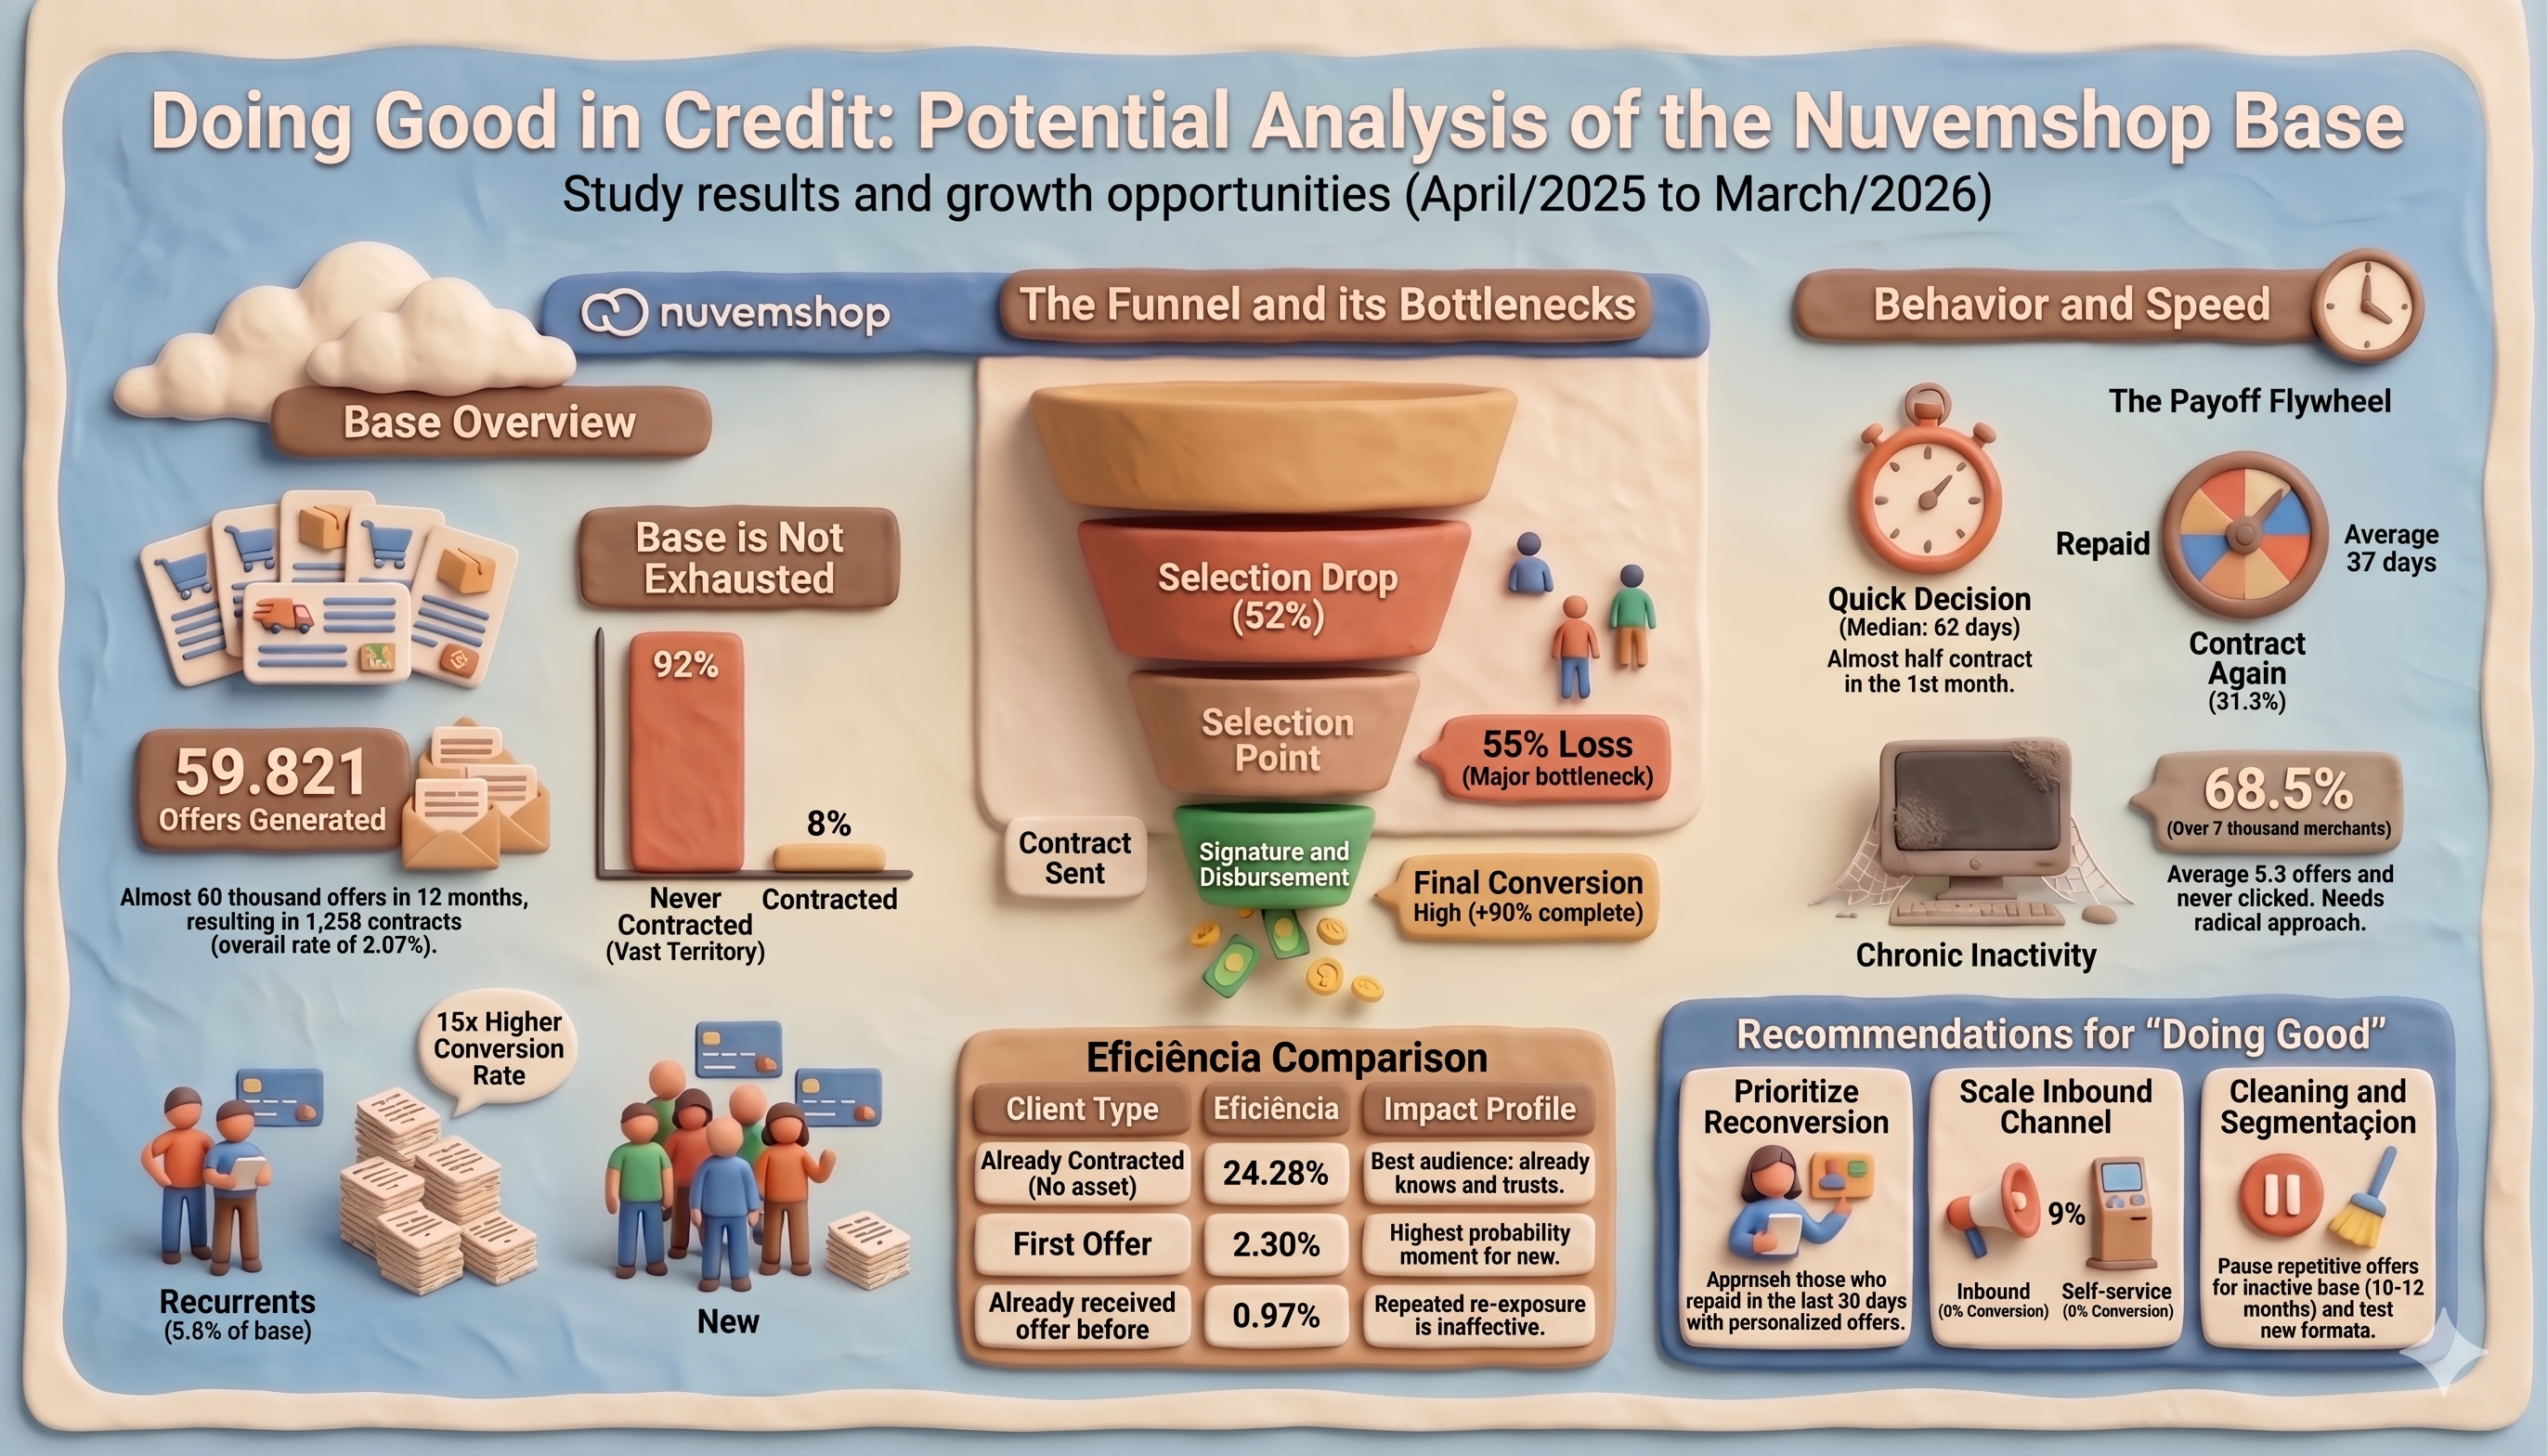
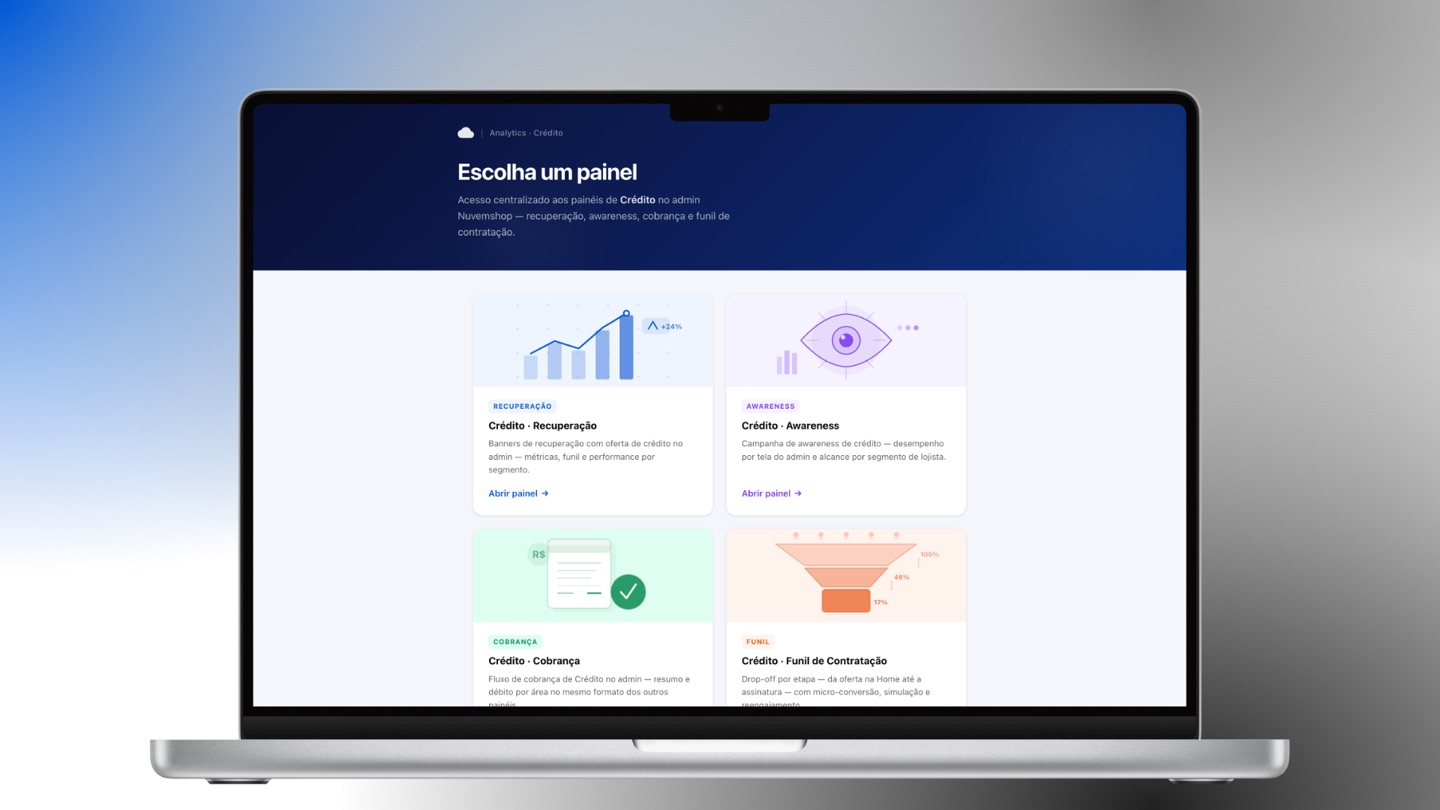
Twelve months of data (Apr/2025 to Mar/2026) covering almost 60 thousand offers sent to the active base. We mapped where merchants dropped off, and how much of the base had never been reached at all.Doze meses de dados (abr/2025 a mar/2026) cobrindo quase 60 mil ofertas enviadas à base ativa. Mapeamos onde o lojista desistia e quanto da base nunca tinha sido alcançado.
92% of the base has never taken credit. But merchants who borrowed once come back at 24%, ten times the rate of new ones.92% da base nunca pegou crédito. Mas quem já pegou uma vez volta a 24%, dez vezes mais que lojista novo.
82% drop between receiving the offer and the first click. The offer was arriving and going nowhere.Queda de 82% entre receber a oferta e o primeiro clique. A oferta chegava e morria ali.
An offer turned down once comes back at 0.97%. Re-sending it was wasted effort.Oferta recusada volta a 0,97%. Reenviar era esforço jogado fora.
The problem was never the number of offers — it was who they went to. Overall conversion sat at 2.07%, and that average hid three very different groups: 24.28% for merchants who had borrowed before, 2.30% for new ones, 0.97% for anyone who had already said no. So we set three priorities: chase the merchants who dropped off recently, let a merchant arrive on their own instead of waiting for an offer, and stop re-sending offers that had already been turned down.O problema nunca foi a quantidade de oferta — era para quem ela ia. A conversão geral era de 2,07%, e essa média escondia três grupos bem diferentes: 24,28% para quem já tinha pegado crédito, 2,30% para lojista novo, 0,97% para quem já tinha dito não. Daí saíram três prioridades: ir atrás de quem desistiu há pouco, deixar o lojista chegar por conta própria em vez de esperar oferta, e parar de reenviar oferta que já foi recusada.
Credit preferences X-rayRaio-X de preferências de crédito
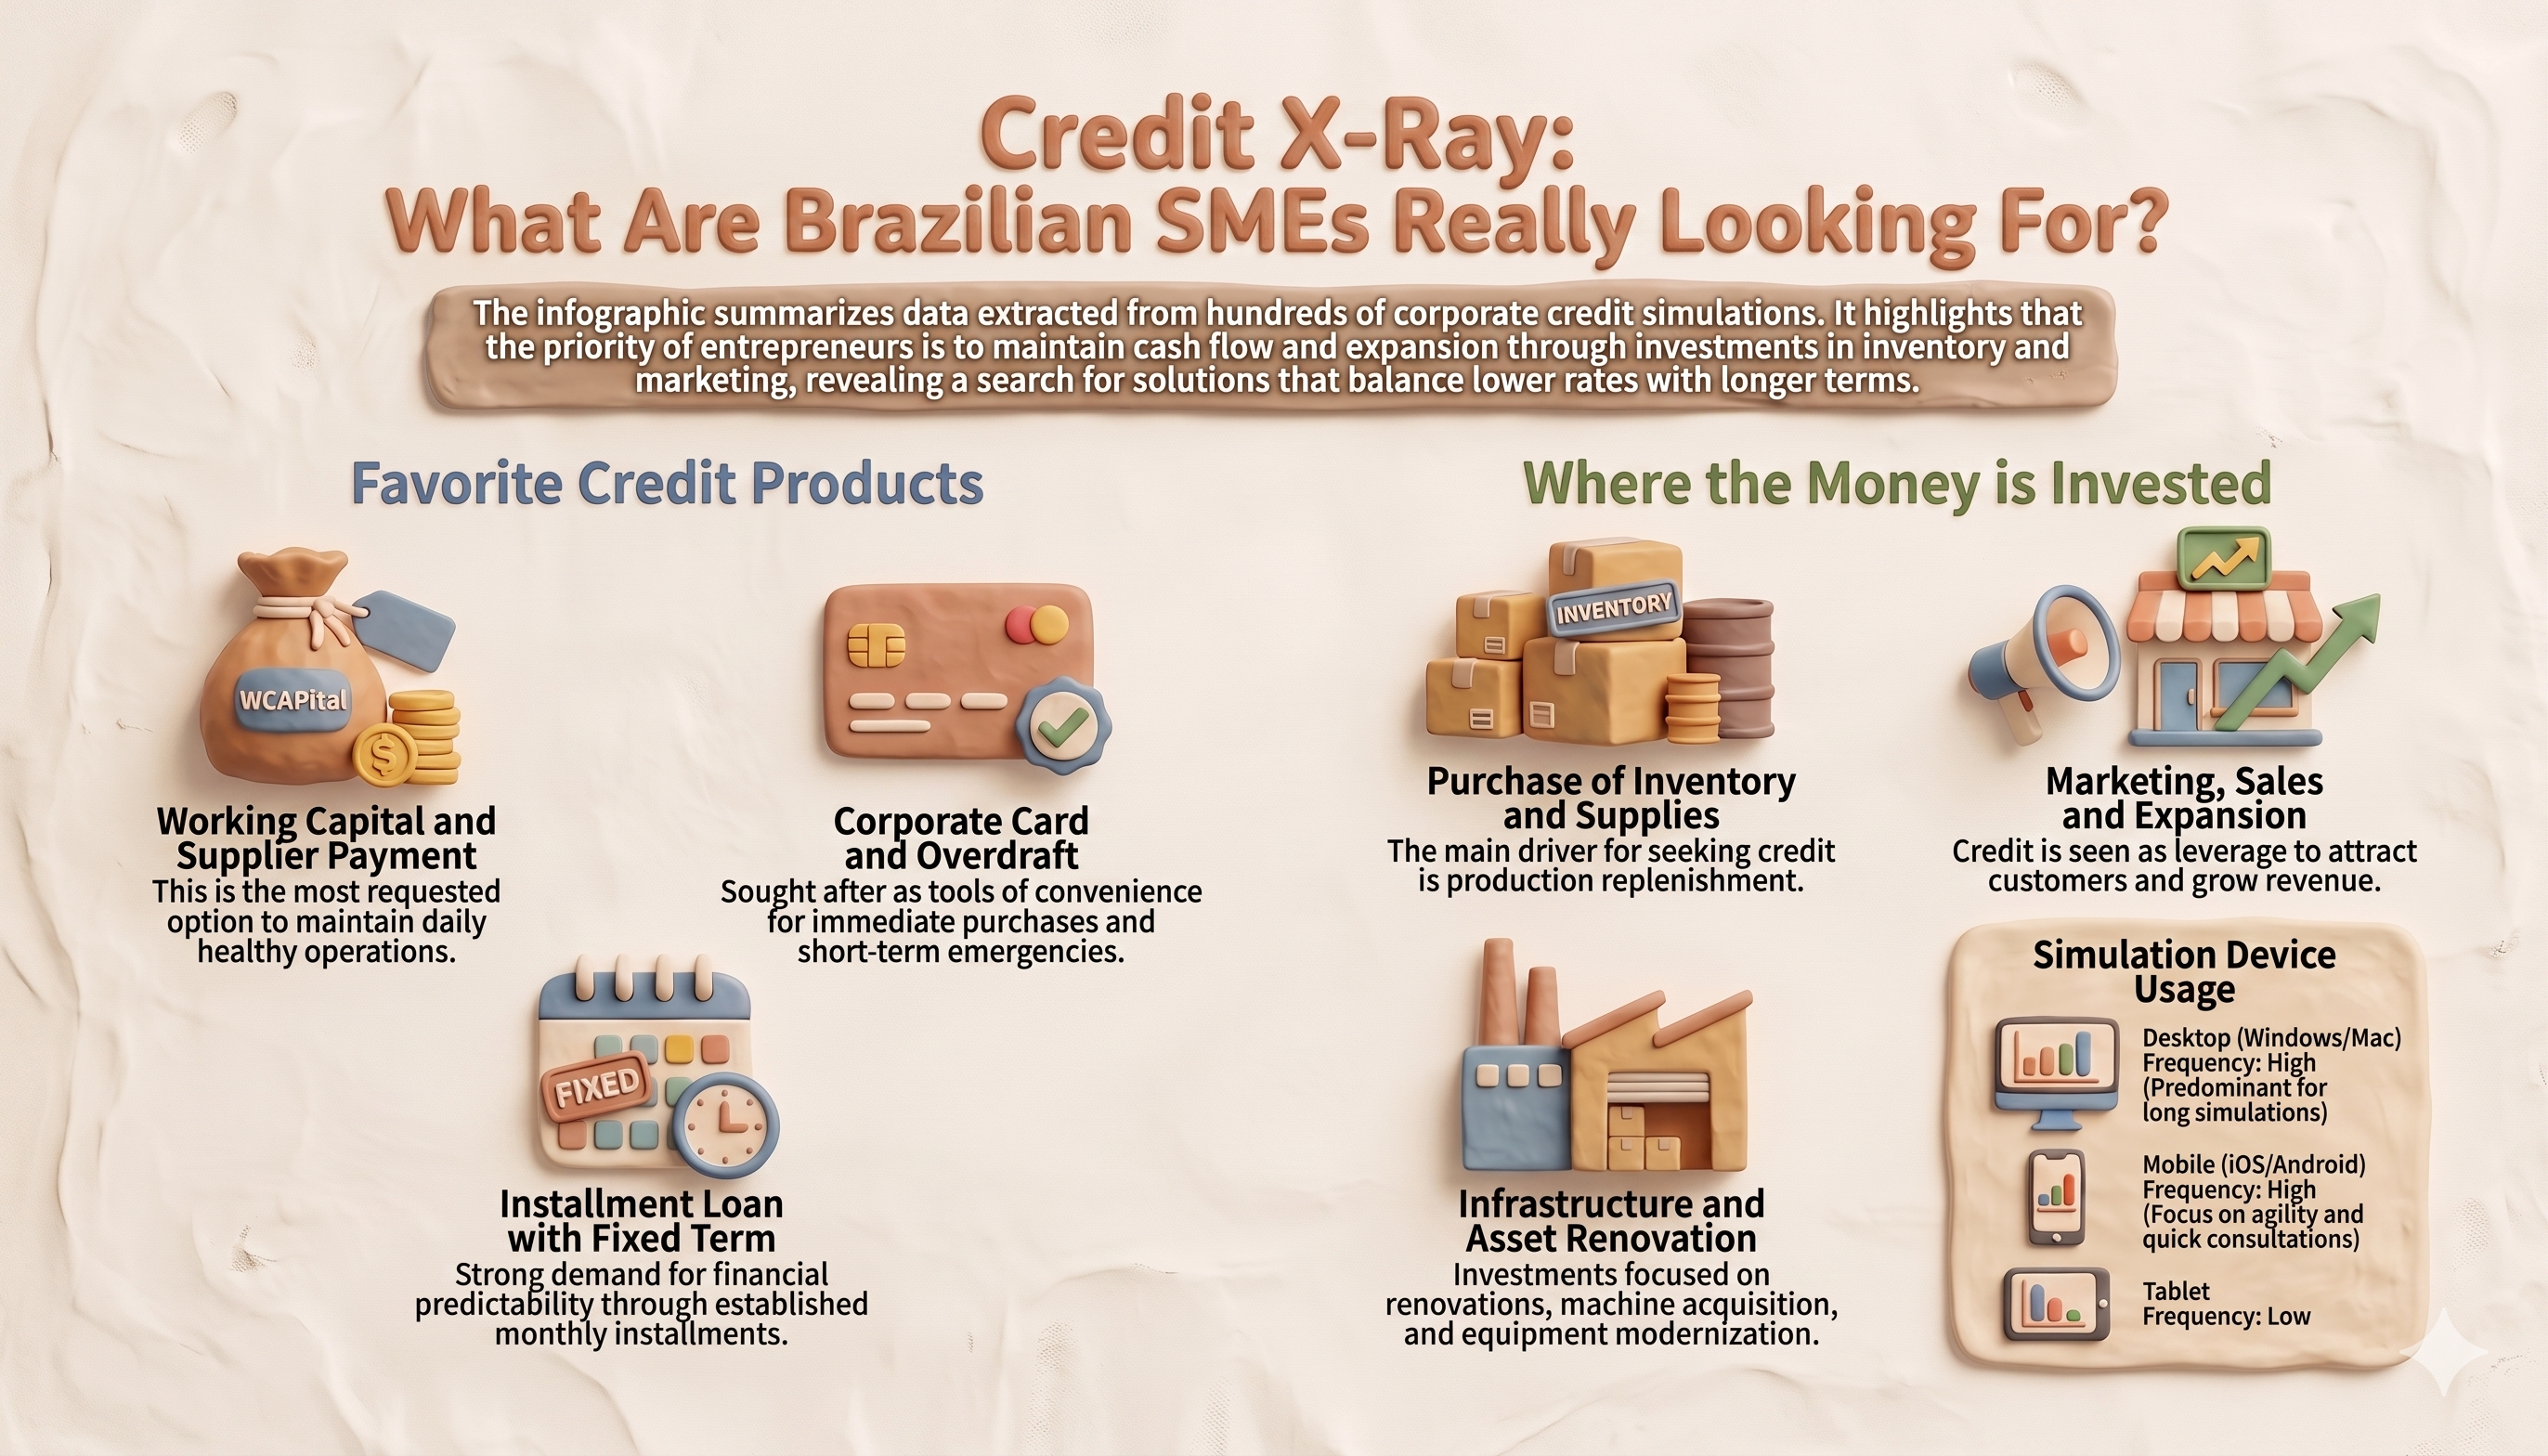
Hundreds of business credit simulations run by Brazilian small businesses. We looked at what they searched for, where the money actually went, and what the device they used said about how urgent it was.Centenas de simulações de crédito empresarial feitas por pequenos negócios brasileiros. Olhamos o que eles buscavam, para onde o dinheiro ia de fato e o que o aparelho usado dizia sobre a pressa.
Working capital is what merchants search for. Inventory is where the money ends up. They ask for one thing and spend it on another.Capital de giro é o que o lojista busca. Estoque é onde o dinheiro realmente vai. Ele pede uma coisa e gasta em outra.
Fixed term wins by a wide margin. Merchants would rather know the instalment than be able to negotiate it.Prazo fixo ganha com folga. O lojista prefere saber o valor da parcela do que poder negociá-la.
Merchants who simulate on the phone are putting out a fire. On desktop, they are planning ahead.Quem simula no celular está apagando incêndio. No computador, está planejando.
The interviews kept landing on the same three things. Merchants wanted to see the full cost before signing. The jump from Nuvemshop to Mova broke the sense of one product. And following the contract was part of the product — the months after signing were where merchants felt lost.As entrevistas caíam sempre nas mesmas três coisas. O lojista queria ver o custo cheio antes de assinar. O salto da Nuvemshop para a Mova quebrava a sensação de produto único. E acompanhar o contrato era parte do produto — era nos meses depois da assinatura que o lojista se perdia.
Merchant financial cycle & credit triggersCiclo financeiro do lojista e gatilhos de crédito
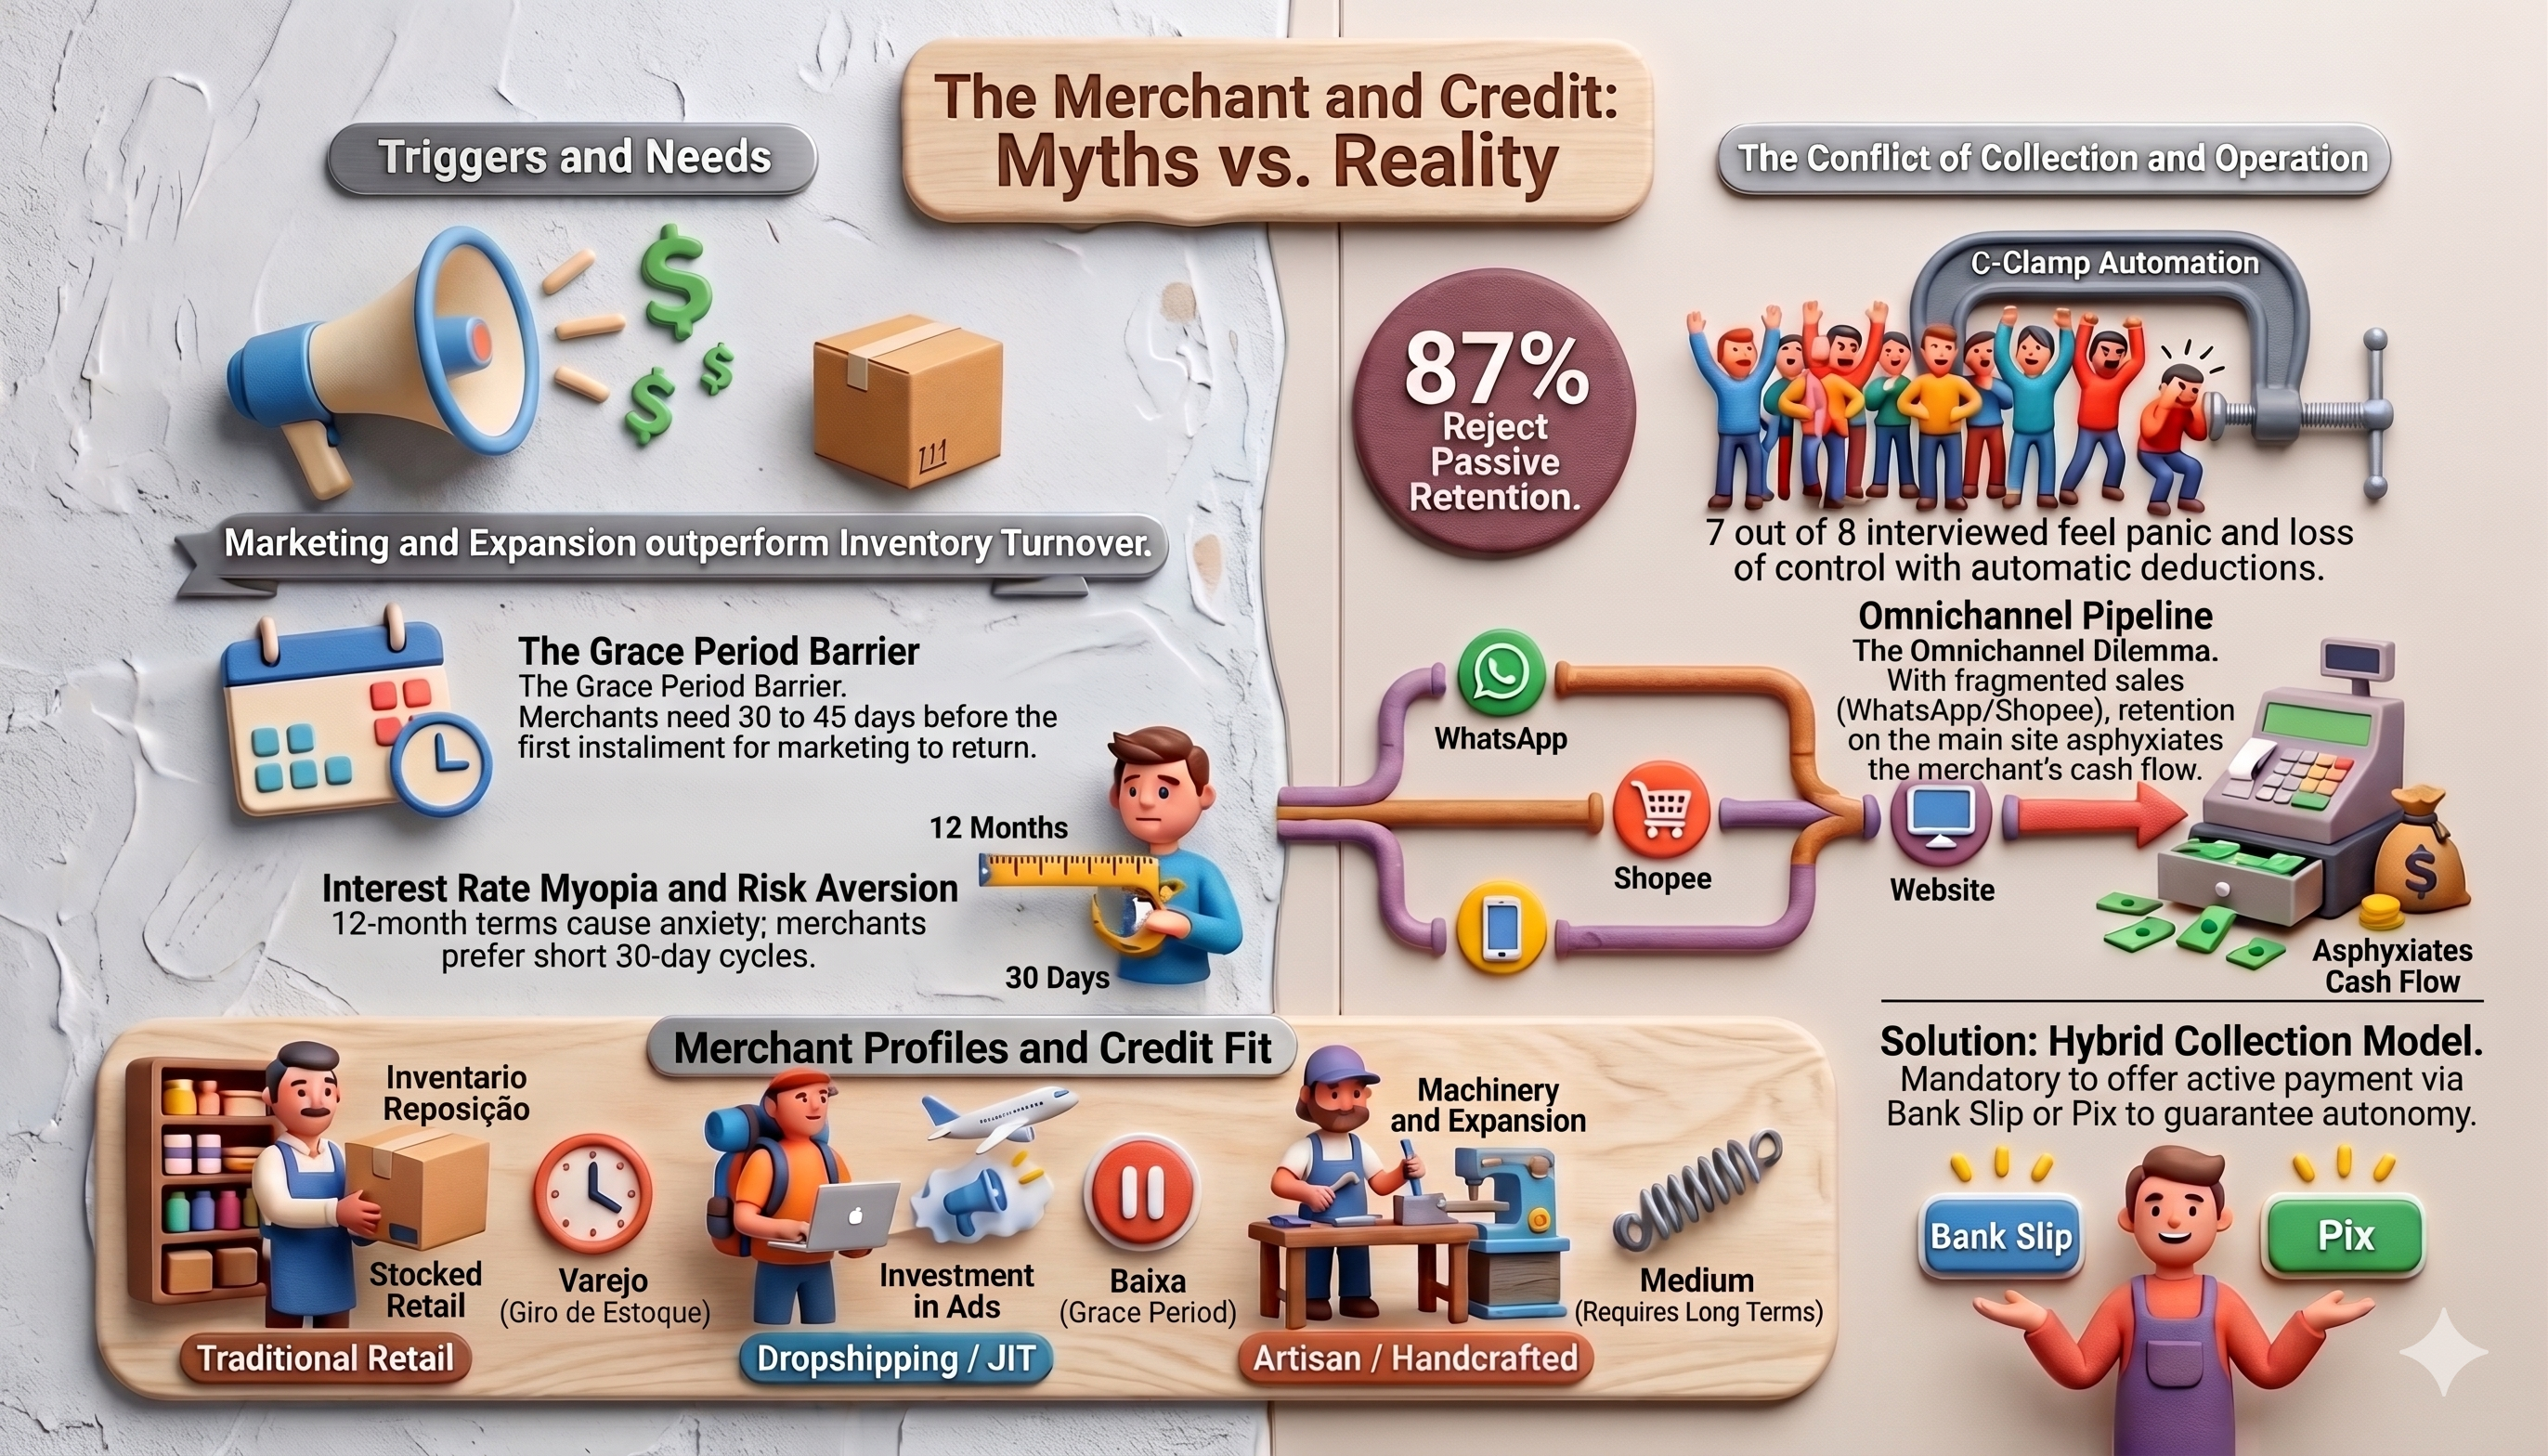
Eight in-depth interviews. We wanted to know how a merchant covers a cash gap today, what gets in the way when they try, and what the credit they actually want would look like.Oito entrevistas em profundidade. Queríamos saber como o lojista cobre um buraco de caixa hoje, o que atrapalha quando ele tenta e como seria o crédito que ele de fato quer.
Cash cycle and trigger. When the pressure peaks, when it last happened, and where the merchant went looking for relief.Ciclo de caixa e gatilho. Quando a pressão aperta, quando foi a última vez e onde o lojista foi buscar alívio.
What weighs in the choice. Final cost, flexibility or limit, and which of the three the merchant gives up first.O que pesa na escolha. Custo final, flexibilidade ou limite, e de qual dos três o lojista abre mão primeiro.
Billing versus convenience. Whether taking the instalment straight out of sales feels like relief or like losing control of the cash, compared with paying by Pix or boleto.Cobrança x conveniência. Se descontar a parcela direto das vendas soa como alívio ou como perder o controle do caixa, comparado a pagar por Pix ou boleto.
From debt to growth: changing how credit is talked aboutDe dívida a crescimento: mudando como se fala de crédito
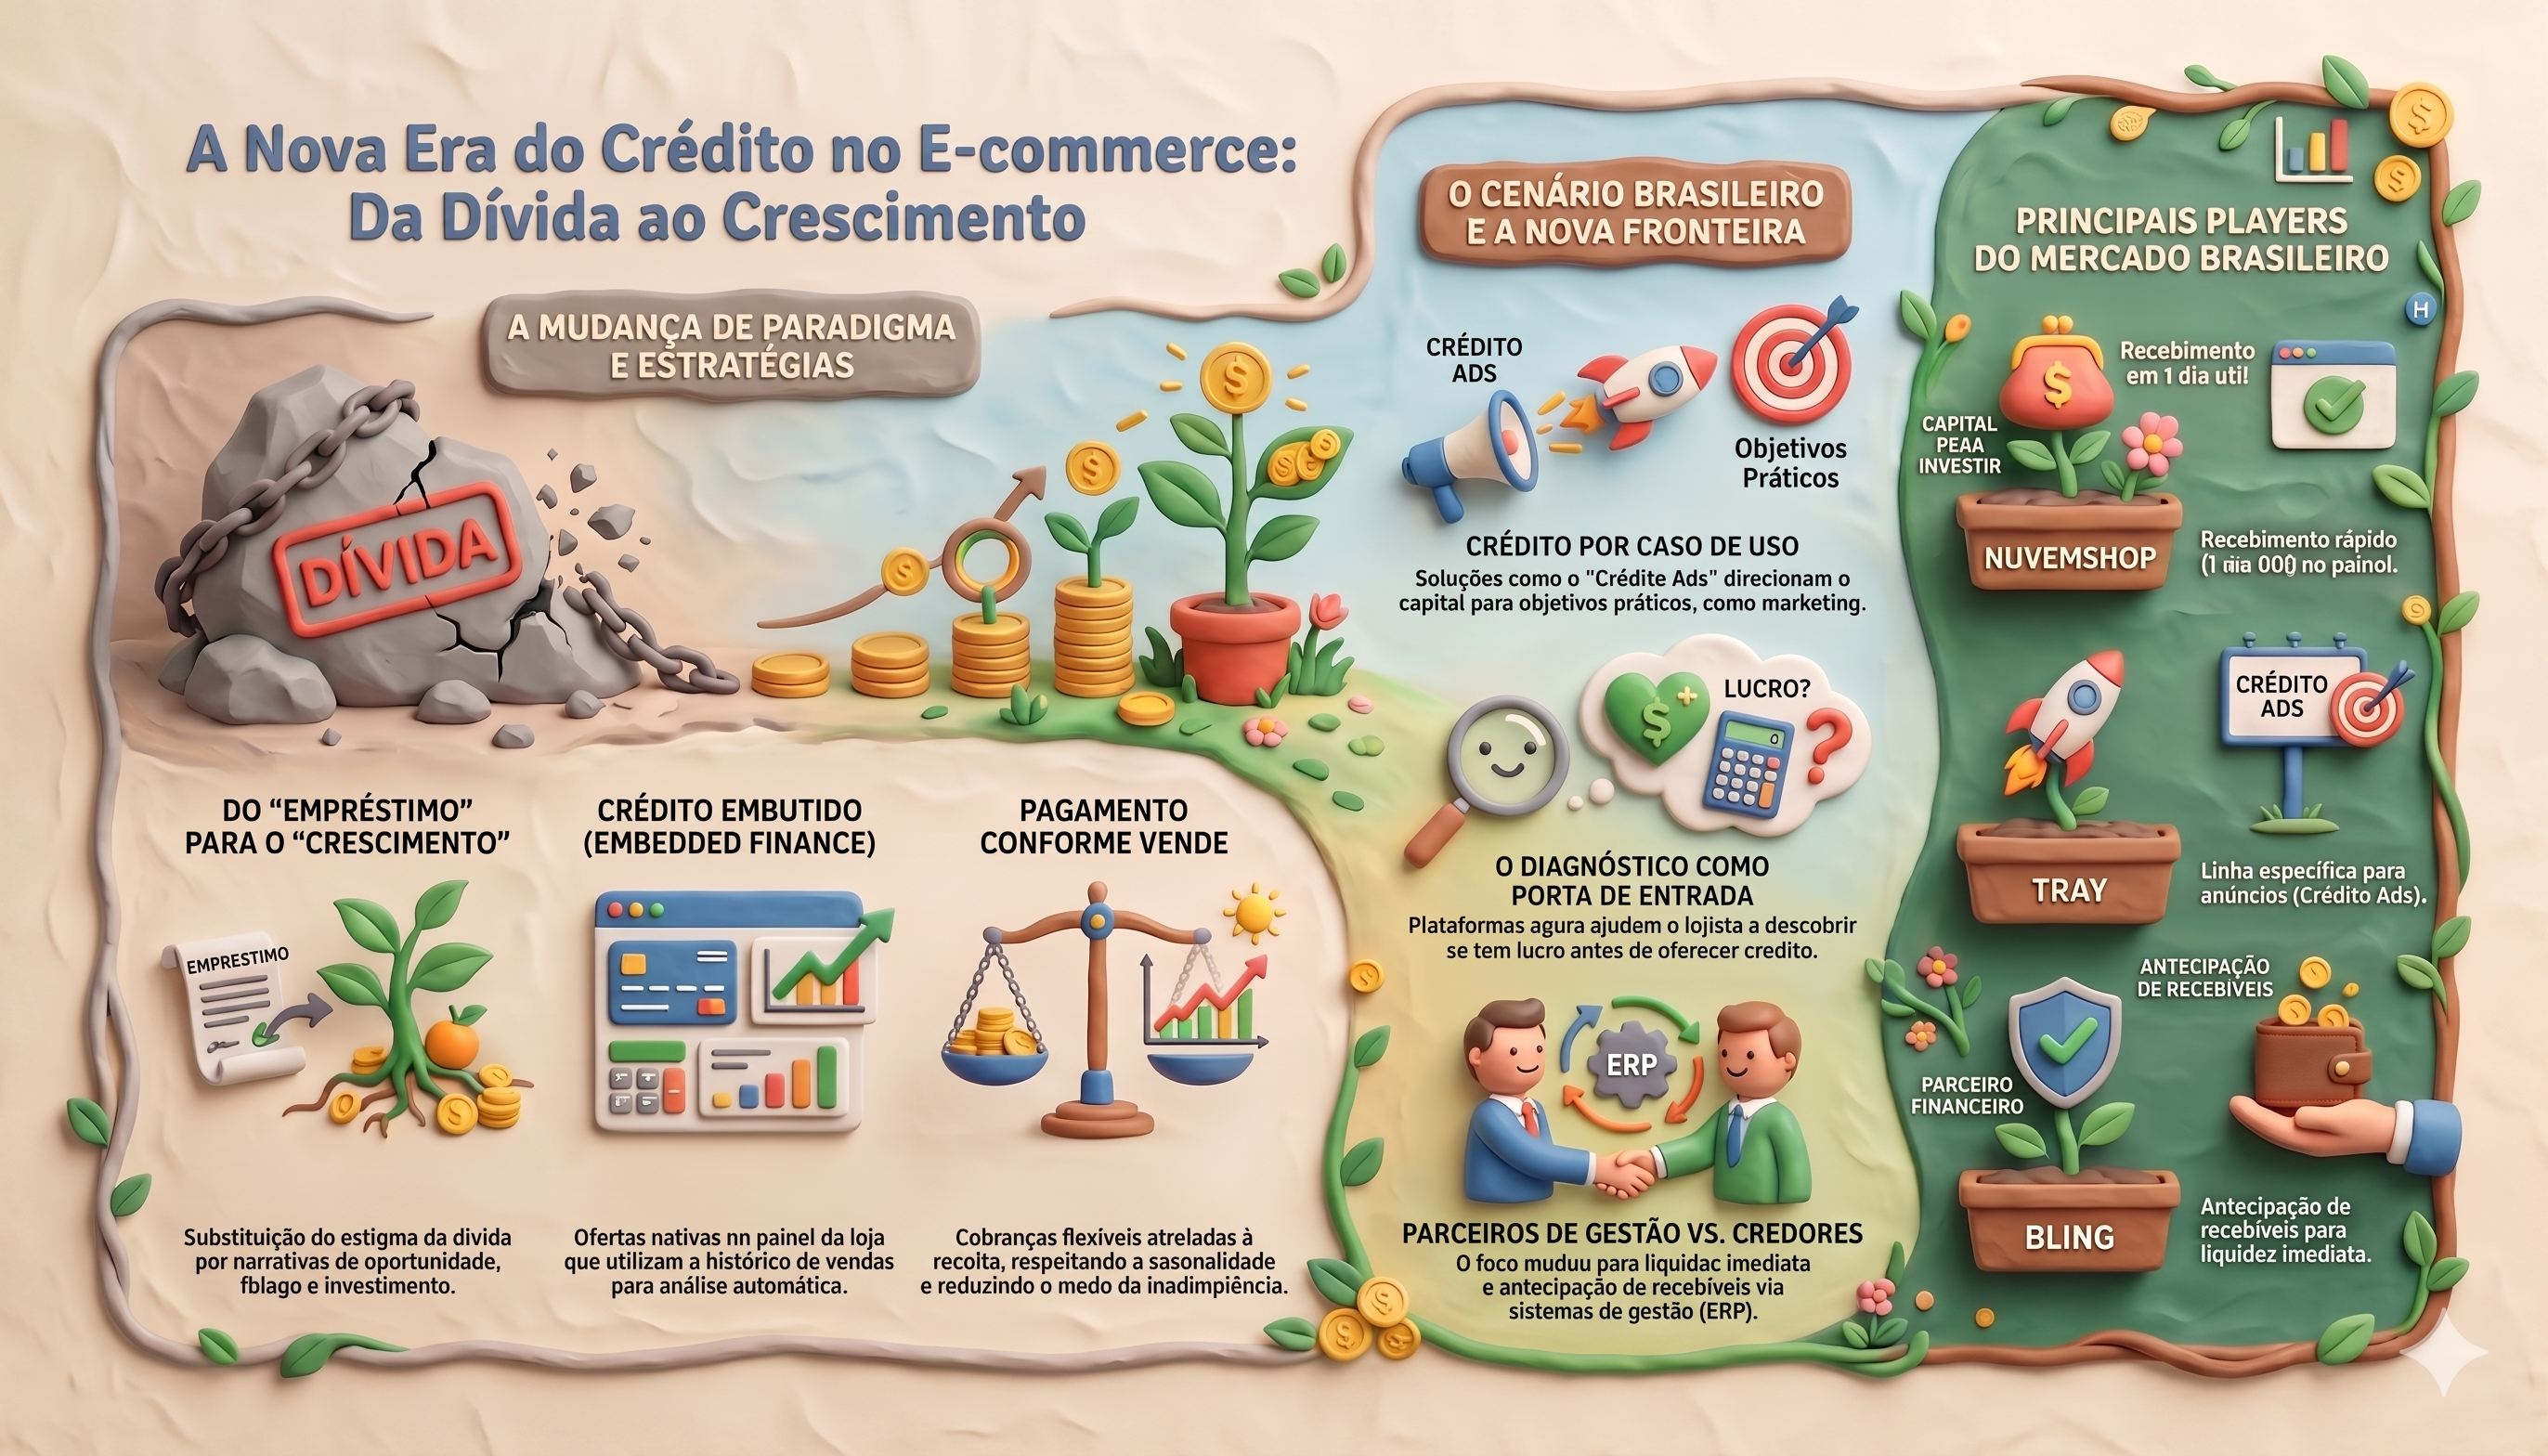
A study on how Nuvemshop talks about credit. The offer was written like a bank product — rate, term, limit. We mapped what is shifting in embedded finance and in the Brazilian market, and what the offer could say instead.Um estudo sobre como a Nuvemshop fala de crédito. A oferta era escrita como produto de banco — taxa, prazo, limite. Mapeamos o que está mudando no crédito embutido e no mercado brasileiro, e o que a oferta poderia dizer no lugar.
Show the merchant their own margin before offering credit. It also screens out whoever should not be borrowing yet.Mostrar ao lojista a própria margem antes de oferecer crédito. De quebra, filtra quem ainda não deveria tomar empréstimo.
Merchants respond better when the offer talks about growth and investment instead of debt.O lojista responde melhor quando a oferta fala de crescimento e investimento em vez de dívida.
Charging as the merchant sells cuts the fear of falling behind, and ties what the platform earns to what the store earns.Cobrar conforme o lojista vende corta o medo de atrasar e amarra o que a plataforma ganha ao que a loja ganha.
Bets & ExperimentsApostas e experimentos
That gave us three bets, and all three shipped — one at a time, over the course of a year. Two were navigable prototypes before that; they are open below. The third is a design spec.Chegamos a três apostas, e as três foram para produção — uma por vez, ao longo de um ano. Duas viraram protótipo navegável antes disso; estão abertas abaixo. A terceira é especificação de design.
Native credit contracting experienceExperiência nativa de contratação de crédito
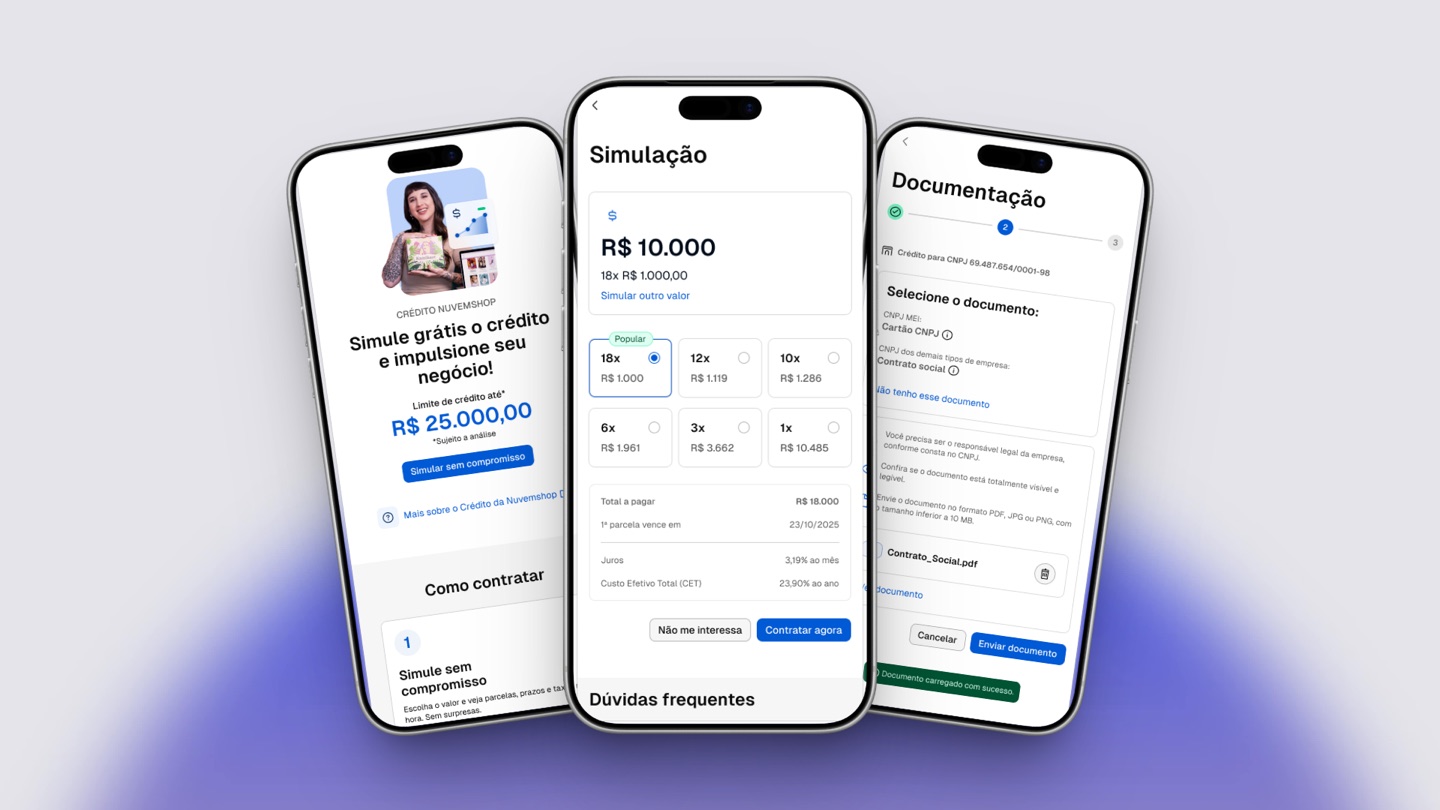
I built the contracting flow with components from Nuvemshop's design system. The merchant sees the full cost before signing, and the wording does not change between the offer and the contract. This is the version merchants tested.Montei a contratação inteira com os componentes do design system da Nuvemshop. O lojista vê o custo cheio antes de assinar, e a linguagem não muda entre a oferta e o contrato. Esta é a versão que os lojistas testaram.
Show the return before the rateMostrar o retorno antes da taxa
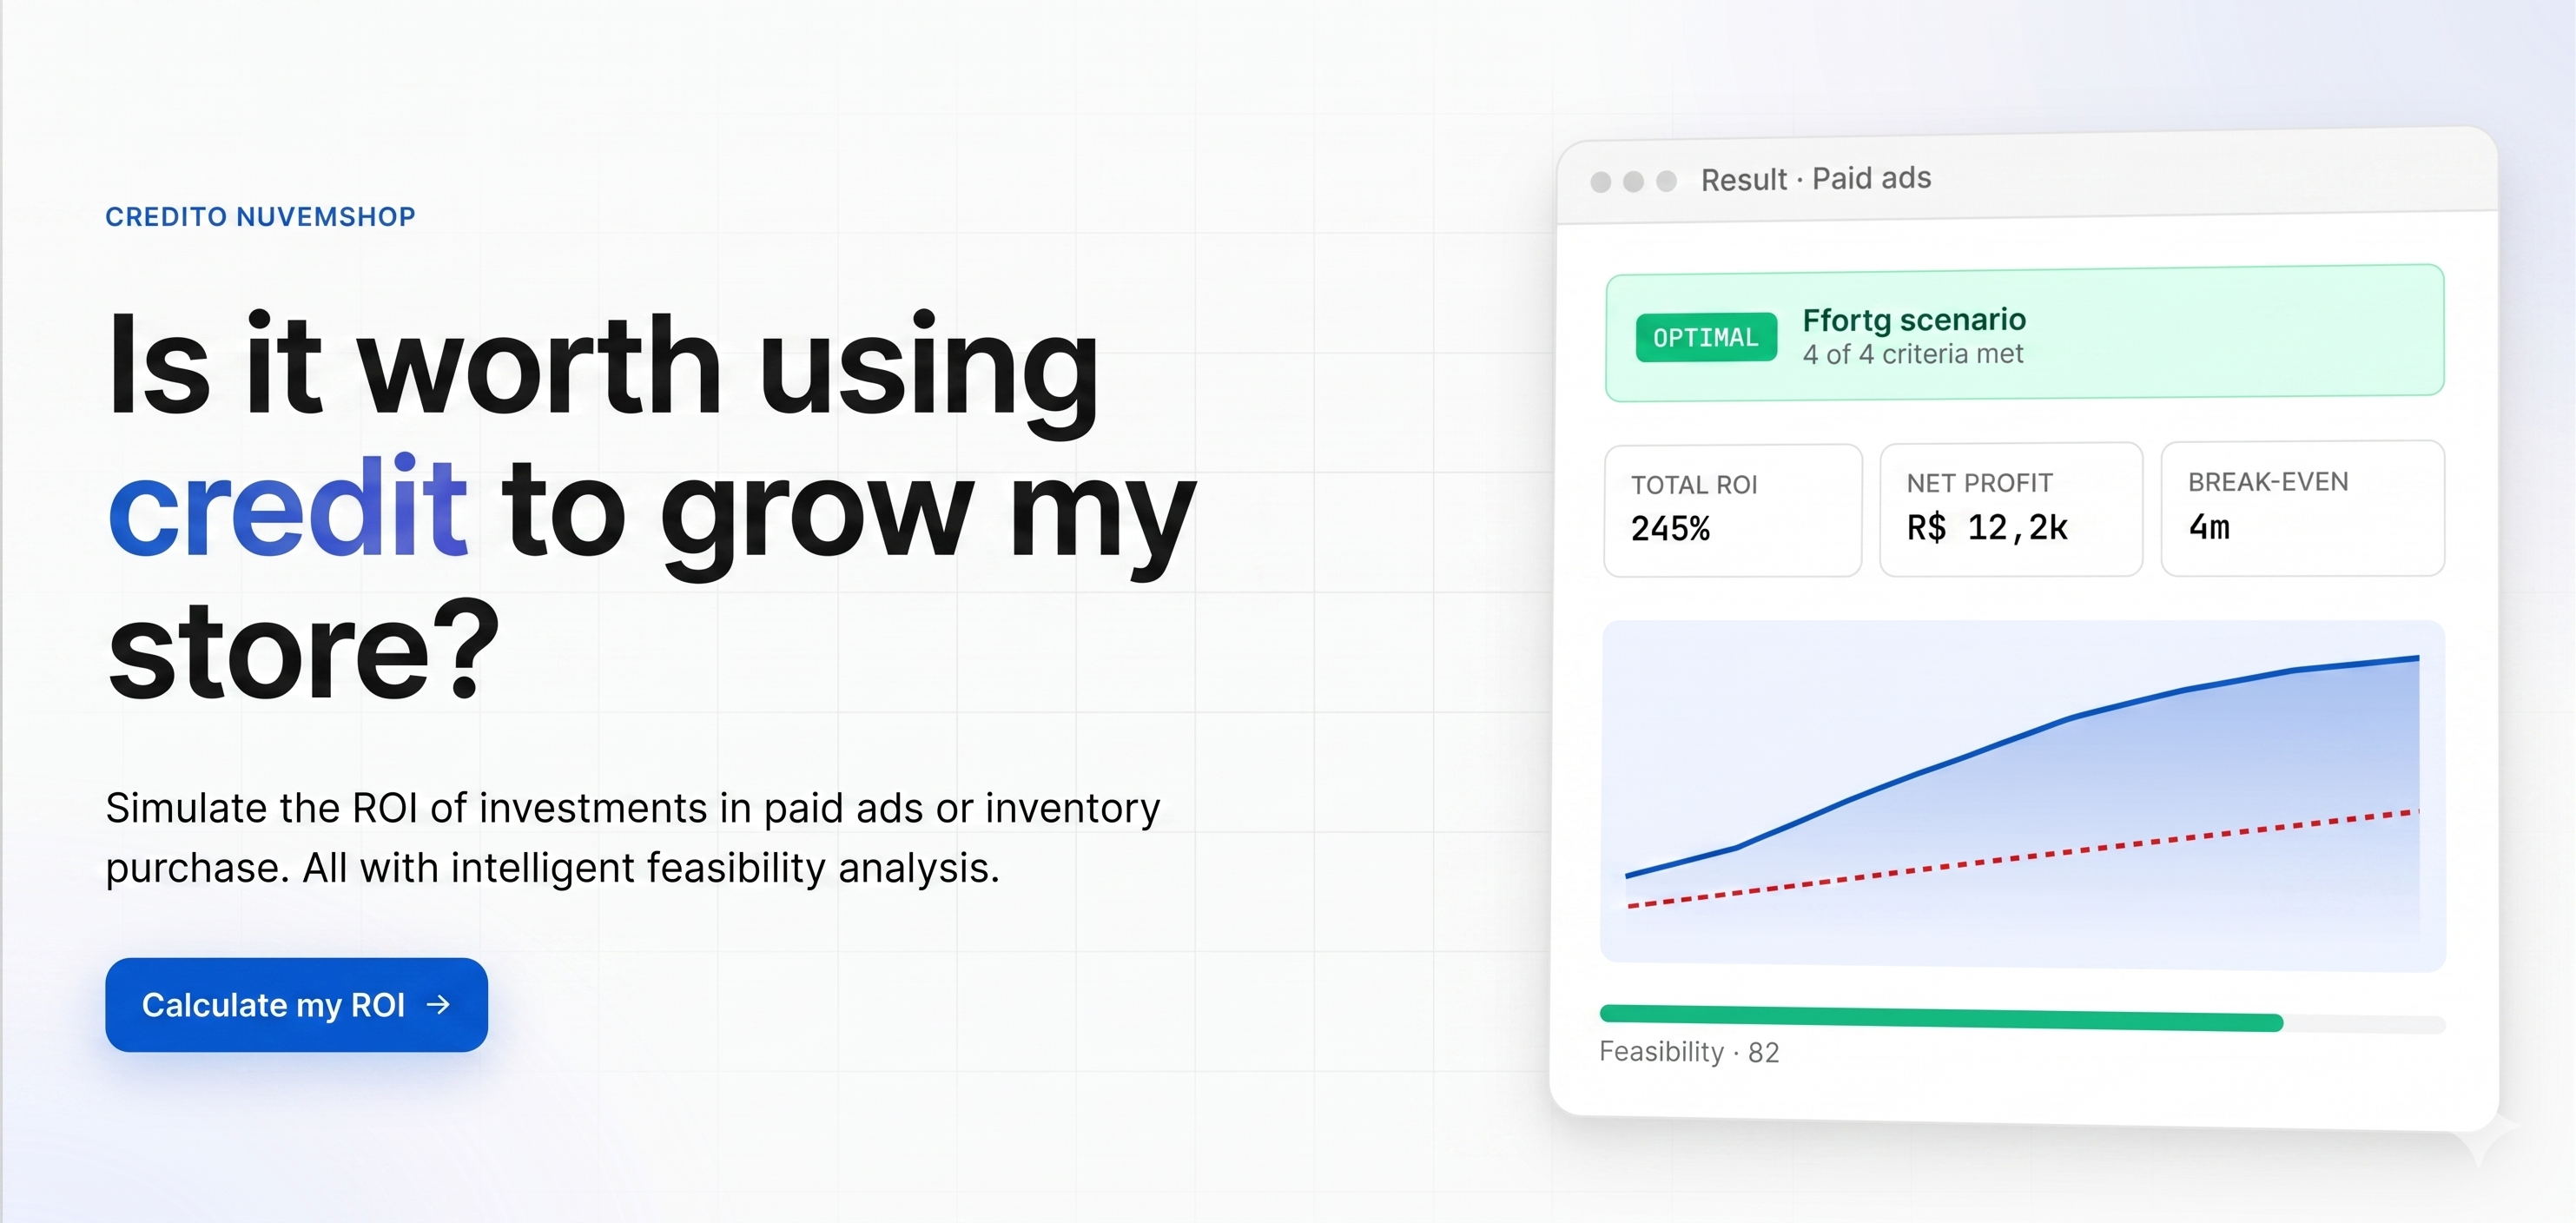
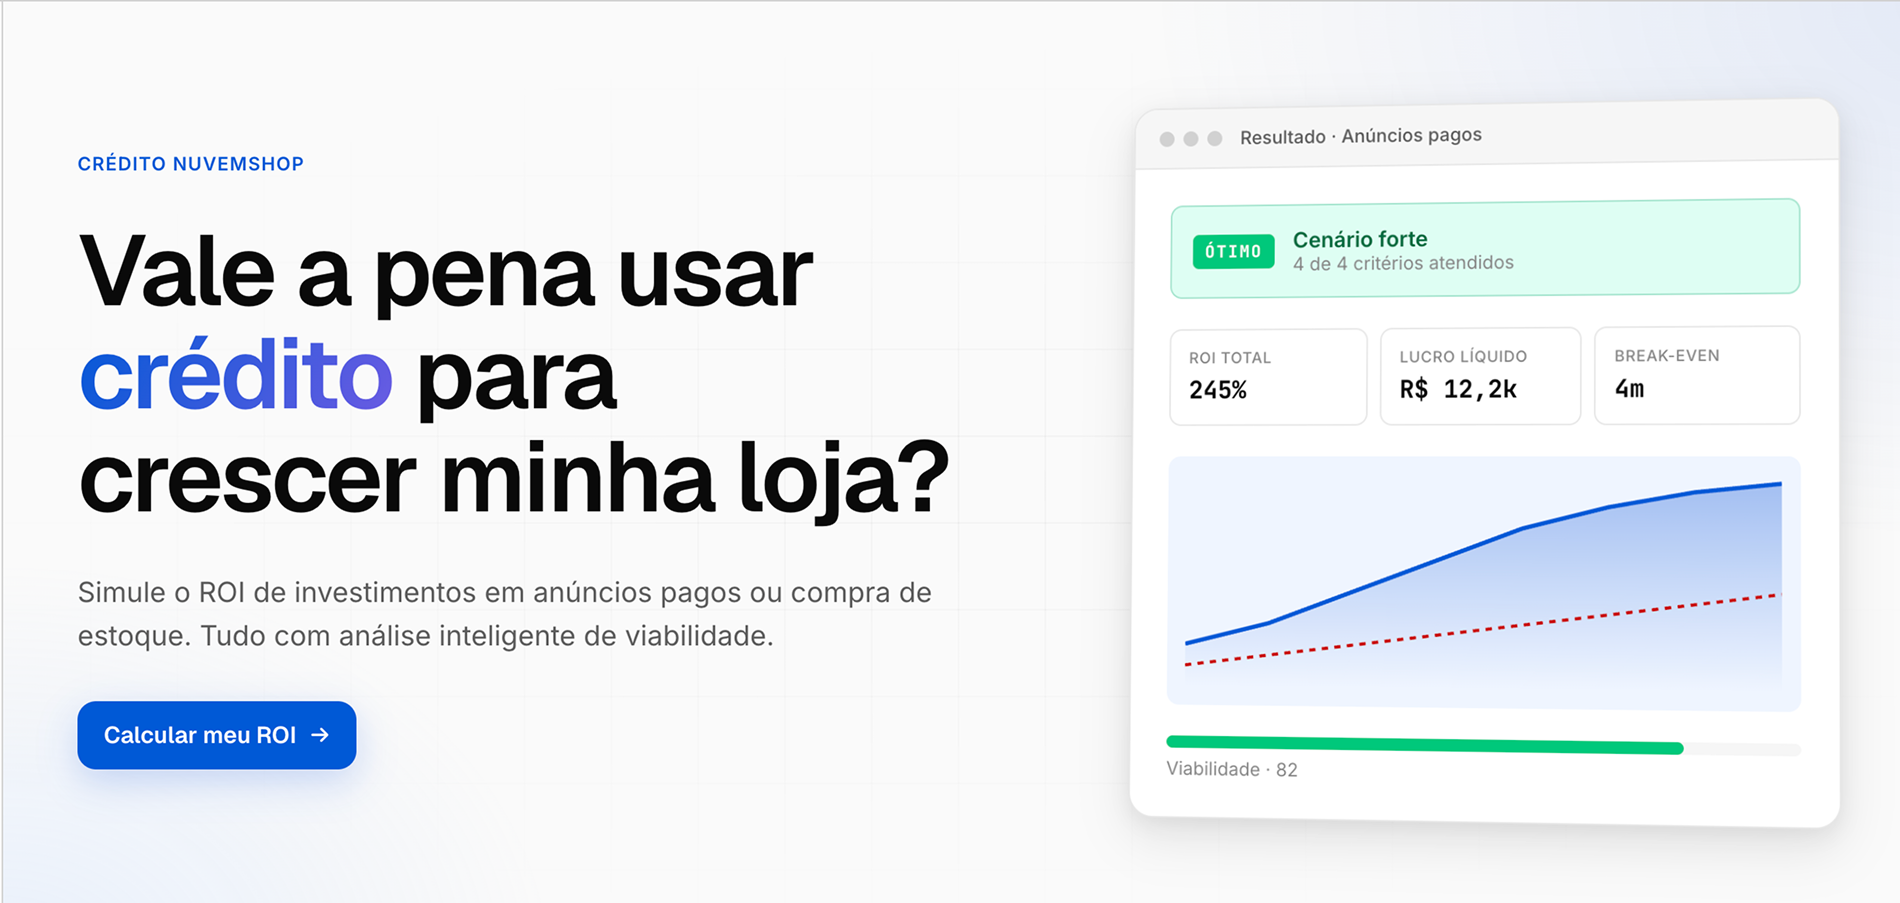
A calculator that opens with return instead of interest rate. The merchant puts in their own numbers and sees whether the loan pays for itself before asking for it.Uma calculadora que começa pelo retorno, em vez da taxa. O lojista põe os próprios números e vê se o empréstimo se paga antes de pedir.
One place to follow the contractUm lugar para acompanhar o contrato
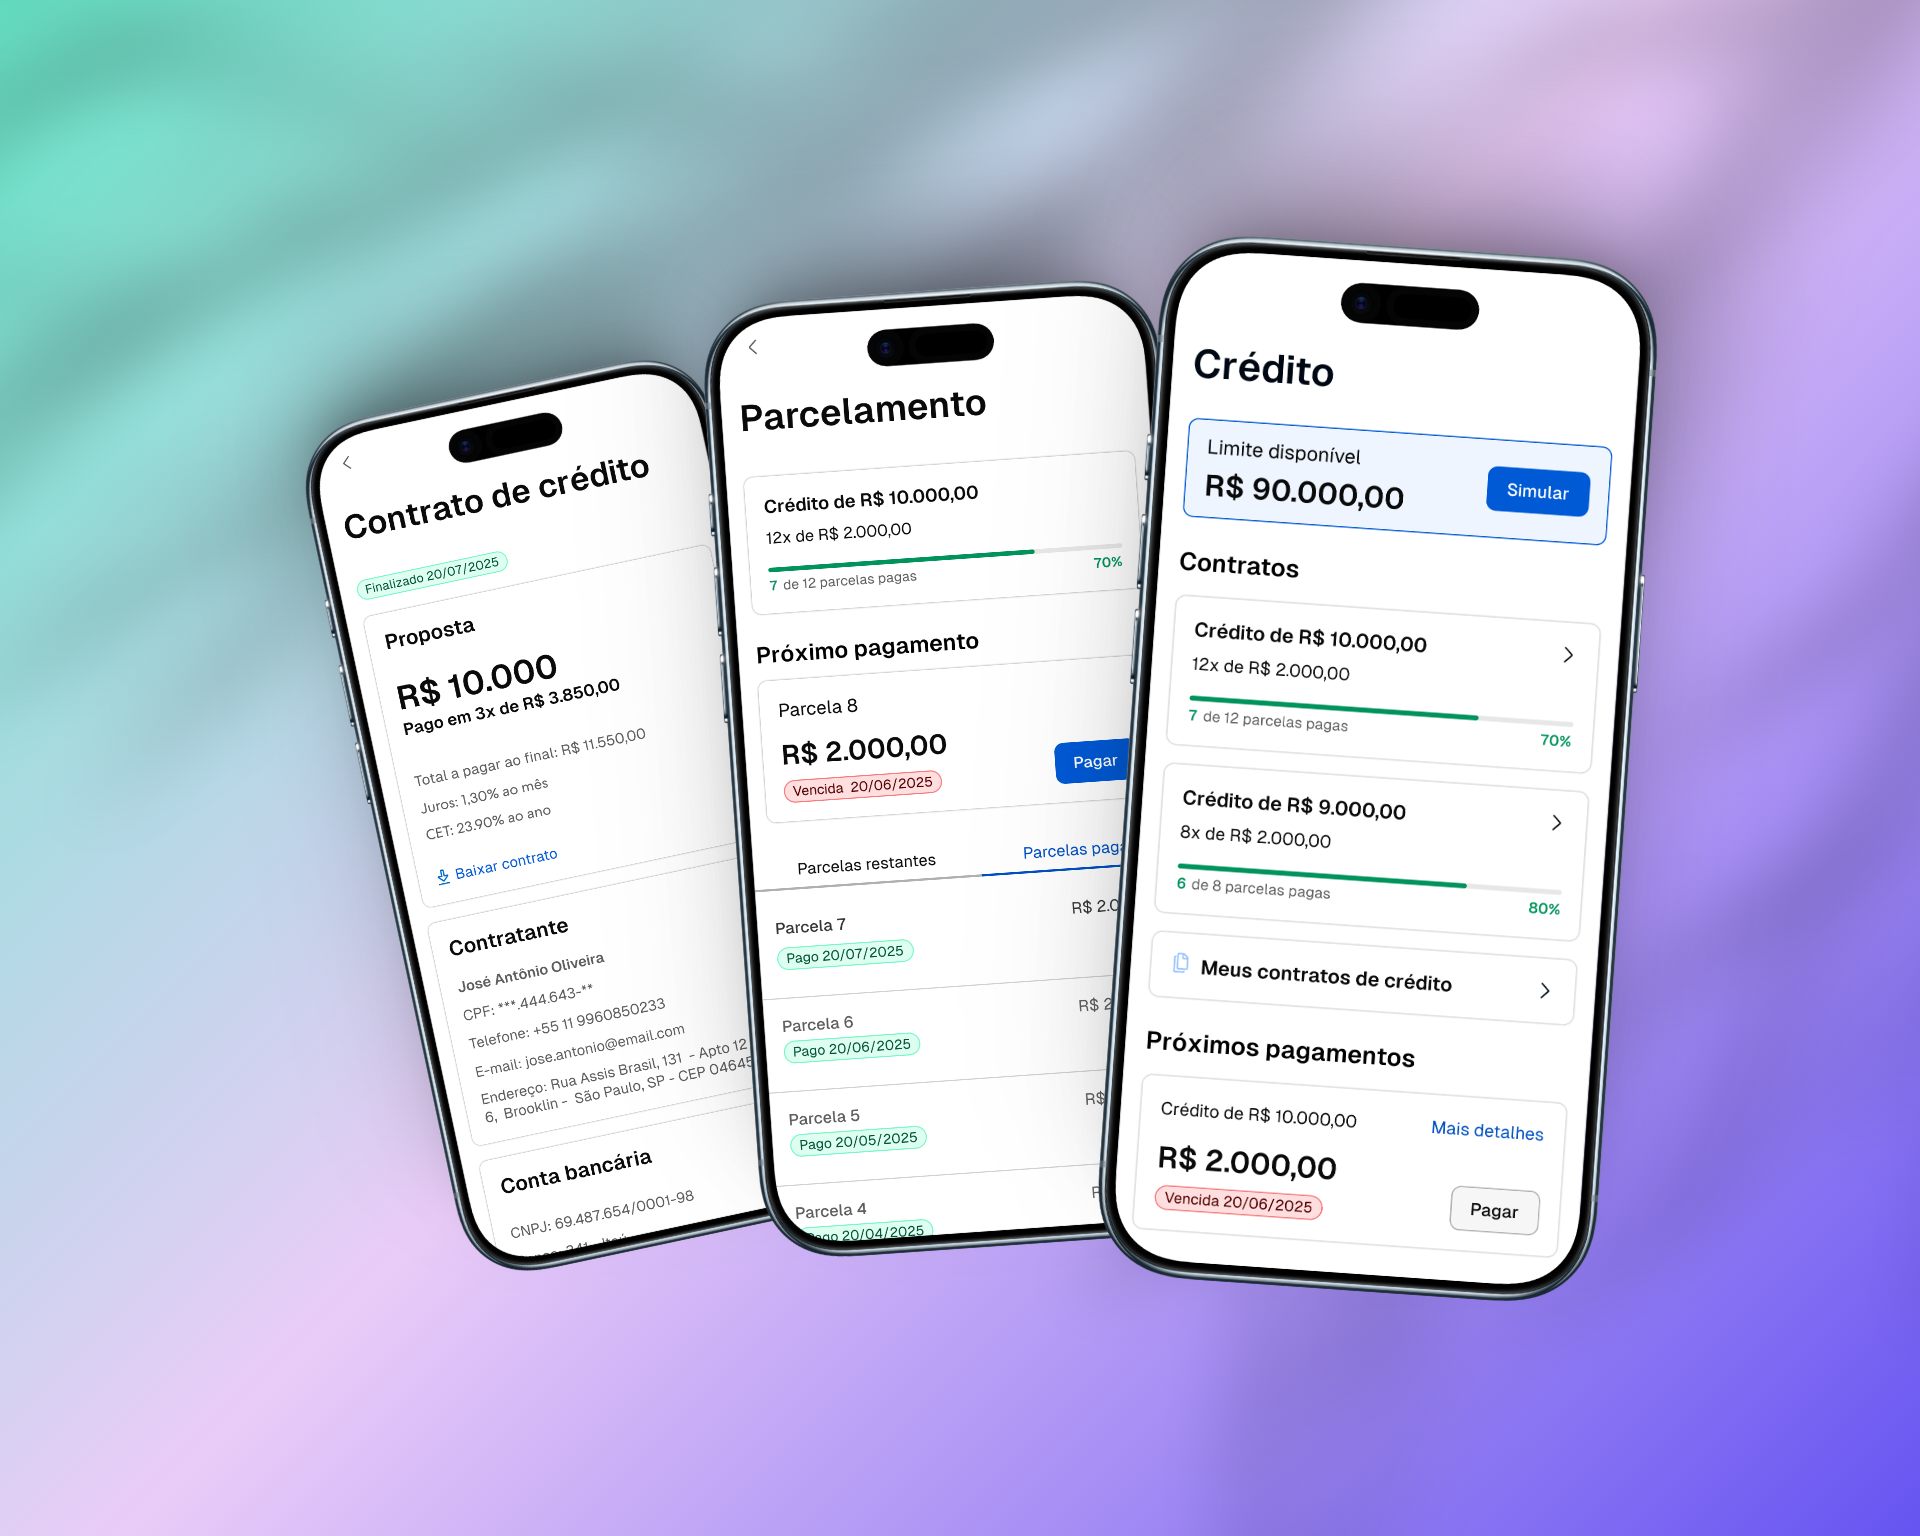
Where the merchant follows the contract, sees what has already been paid and asks for a renewal without calling support. This is the renewal blocker from the research, answered.Onde o lojista acompanha o contrato, vê o que já pagou e pede renovação sem ligar para o suporte. É a trava de renovação da pesquisa, resolvida.